Iran’s Helium Shortage Crisis Threatening Global Chip Supply
Iran Helium Supply Disruption Tests Semiconductor Cooling Chains
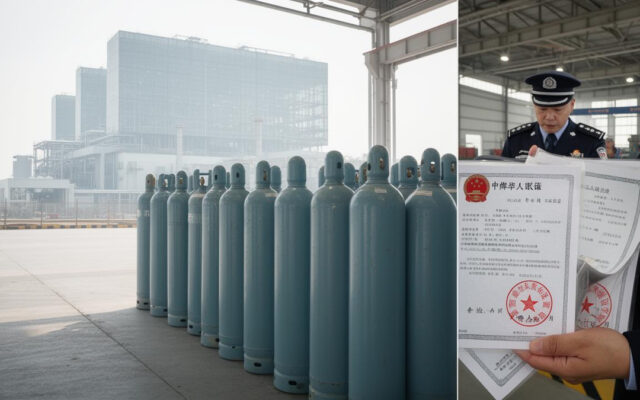
Helium shortages linked to Iranian supply disruptions are exposing a structural weak point in semiconductor manufacturing, where the gas performs functions that no alternative can replicate at the process level required for advanced nodes.
The issue centers on helium’s unique physical properties. With a boiling point at minus 269 degrees Celsius and thermal conductivity roughly six times higher than air, the gas plays a non-negotiable role in wafer cooling, chemical vapor deposition and advanced packaging processes. Its molecular diameter is the smallest of any industrial gas, a trait that makes it indispensable in vacuum leak detection and ultra-high-purity environments.
Five applications dominate helium use in chip fabrication. Silicon wafer cooling during plasma etching relies on helium to prevent thermal warping. Chemical vapor deposition uses it as a carrier gas because of its inert chemistry. Advanced packaging at 3nm and 2nm nodes, including CoWoS technology, demands zero oxidation tolerance that only helium can deliver. EUV photolithography environments require atmospheric purity that eliminates all other candidates. Vacuum leak detection depends on helium’s molecular size, which no substitute matches.
According to OilPrice.com, helium’s thermal conductivity enables the fast, precise cooling needed to shrink circuitry in advanced chips, while its inertness protects semiconductor purity throughout fabrication.
Shortages tied to Iran have begun to ripple through supply chains. The country’s role in global helium output has historically been modest but regionally significant. Disruptions there intersect with a market already characterized by tight supply and long lead times for new production capacity.
Helium is not treated as a strategic input in most corporate risk models. It rarely surfaces in earnings calls or boardroom planning documents. Yet the gas underpins production lines from Hsinchu to Seoul. A regional supply shock in one corner of the market can cascade quickly because helium cannot be stockpiled indefinitely at scale and because global liquefaction and distribution infrastructure remains concentrated.
The semiconductor industry has no process workaround. Substitution is blocked by chemistry and physics, not by cost or preference. Nitrogen and argon, the most common alternatives in other industrial applications, lack the thermal properties and molecular characteristics that chipmaking requires. No element on the periodic table replicates helium’s combination of inertness, conductivity and molecular size.
The result is a supply chain with minimal flex. Fabrication schedules depend on consistent helium deliveries, and any gap in feedstock availability threatens utilization rates at facilities producing chips for data centers, automotive systems and consumer electronics.
Market participants have faced helium tightness before, but the current episode coincides with record semiconductor capital expenditure and production ramps at advanced nodes. Demand from MRI systems, aerospace and research laboratories adds further pressure. Spot prices have historically responded sharply to supply shocks, though long-term contracts insulate some buyers.
Iran’s disruption underscores the geographic concentration risk in helium sourcing. Most global supply originates from a handful of liquefaction facilities tied to natural gas extraction. New projects take years to commission, and reserve development is capital-intensive. The market remains structurally tight.
Leave a Reply