Taiwan’s Helium Imports Shift to the U.S. as Geopolitical Risk Reshapes Semiconductor Supply Chains
U.S. Helium Shipments to Taiwan Climb as Buyers Pivot Away From Qatari Supply
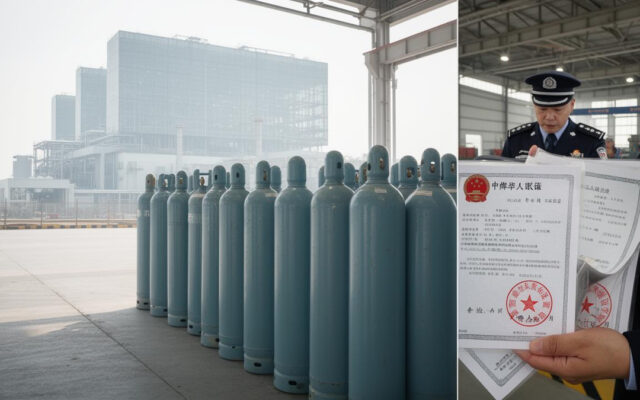
Taiwan’s helium imports from the United States have risen sharply while volumes from Qatar have dropped, according to recent trade data that point to a shift in sourcing strategy among the island’s semiconductor fabricators.
The change is particularly notable given helium’s role in chipmaking and Taiwan’s dominance in global semiconductor production. For much of 2020 through 2024, Qatar served as Taiwan’s primary helium supplier, with monthly shipments climbing steadily and at one point exceeding $20 million per month in 2025, according to the data cited. Those volumes have since fallen during 2026. At the same time, U.S. shipments to Taiwan have moved higher.
The trend does not appear to reflect weaker demand. Semiconductor output remains a strategic priority, and helium — used in cooling, inerting and purification during wafer processing — has no easy substitute at the purity grades required for advanced fabrication.
Instead, the shift suggests that procurement teams are responding to perceived supply risk tied to the Gulf. Helium buyers do not typically wait for formal shortages. When a concentrated source of supply becomes less predictable, volume moves toward alternatives.
The United States holds that position. The country has long been a significant helium producer, supported by large-scale upstream assets including ExxonMobil’s LaBarge facility in Wyoming. That infrastructure now appears to be capturing a larger share of strategically sensitive offtake as buyers seek stable supply outside the Gulf.
Qatar’s Ras Laffan complex has been a cornerstone of global helium supply for years, delivering high-volume feedstock into Asia-Pacific markets. But even well-established supply lanes can shift when geopolitical calculus changes. Trying to lock in non-Gulf volumes ahead of others can mean the difference between uninterrupted production and scrambling in the spot market.
For Taiwan’s chip sector, continuity of specialty gas supply is non-negotiable. Fabrication facilities operate on narrow tolerances, and disruptions to feedstock can cascade through global electronics supply chains. That makes diversification more than a procurement exercise — it becomes a strategic imperative.
The helium market is small compared to LNG or crude oil, but its importance to advanced manufacturing is outsized. Semiconductor production, MRI systems and aerospace all depend on reliable helium supply, yet the number of large-scale producers remains limited.
The latest trade data underline how quickly sourcing patterns can change when risk perceptions shift. Taiwan’s pivot toward U.S. supply does not necessarily signal the end of Qatari volumes, but it does reflect a recalibration of supplier concentration.
For midstream operators and liquefaction facilities in the United States, the shift represents an opportunity to secure long-term contracts with high-value buyers. For Gulf producers, it may serve as a reminder that even established customer relationships require stable operating environments to endure.
Helium supply chains are rarely visible until something breaks. The movement of Taiwan’s import mix suggests that buyers are adjusting before that happens.
Leave a Reply